If your warehouse needs new equipment, financing it lets you start using it now and pay for it over time. That usually suits your cashflow, but it comes with interest and a long commitment.
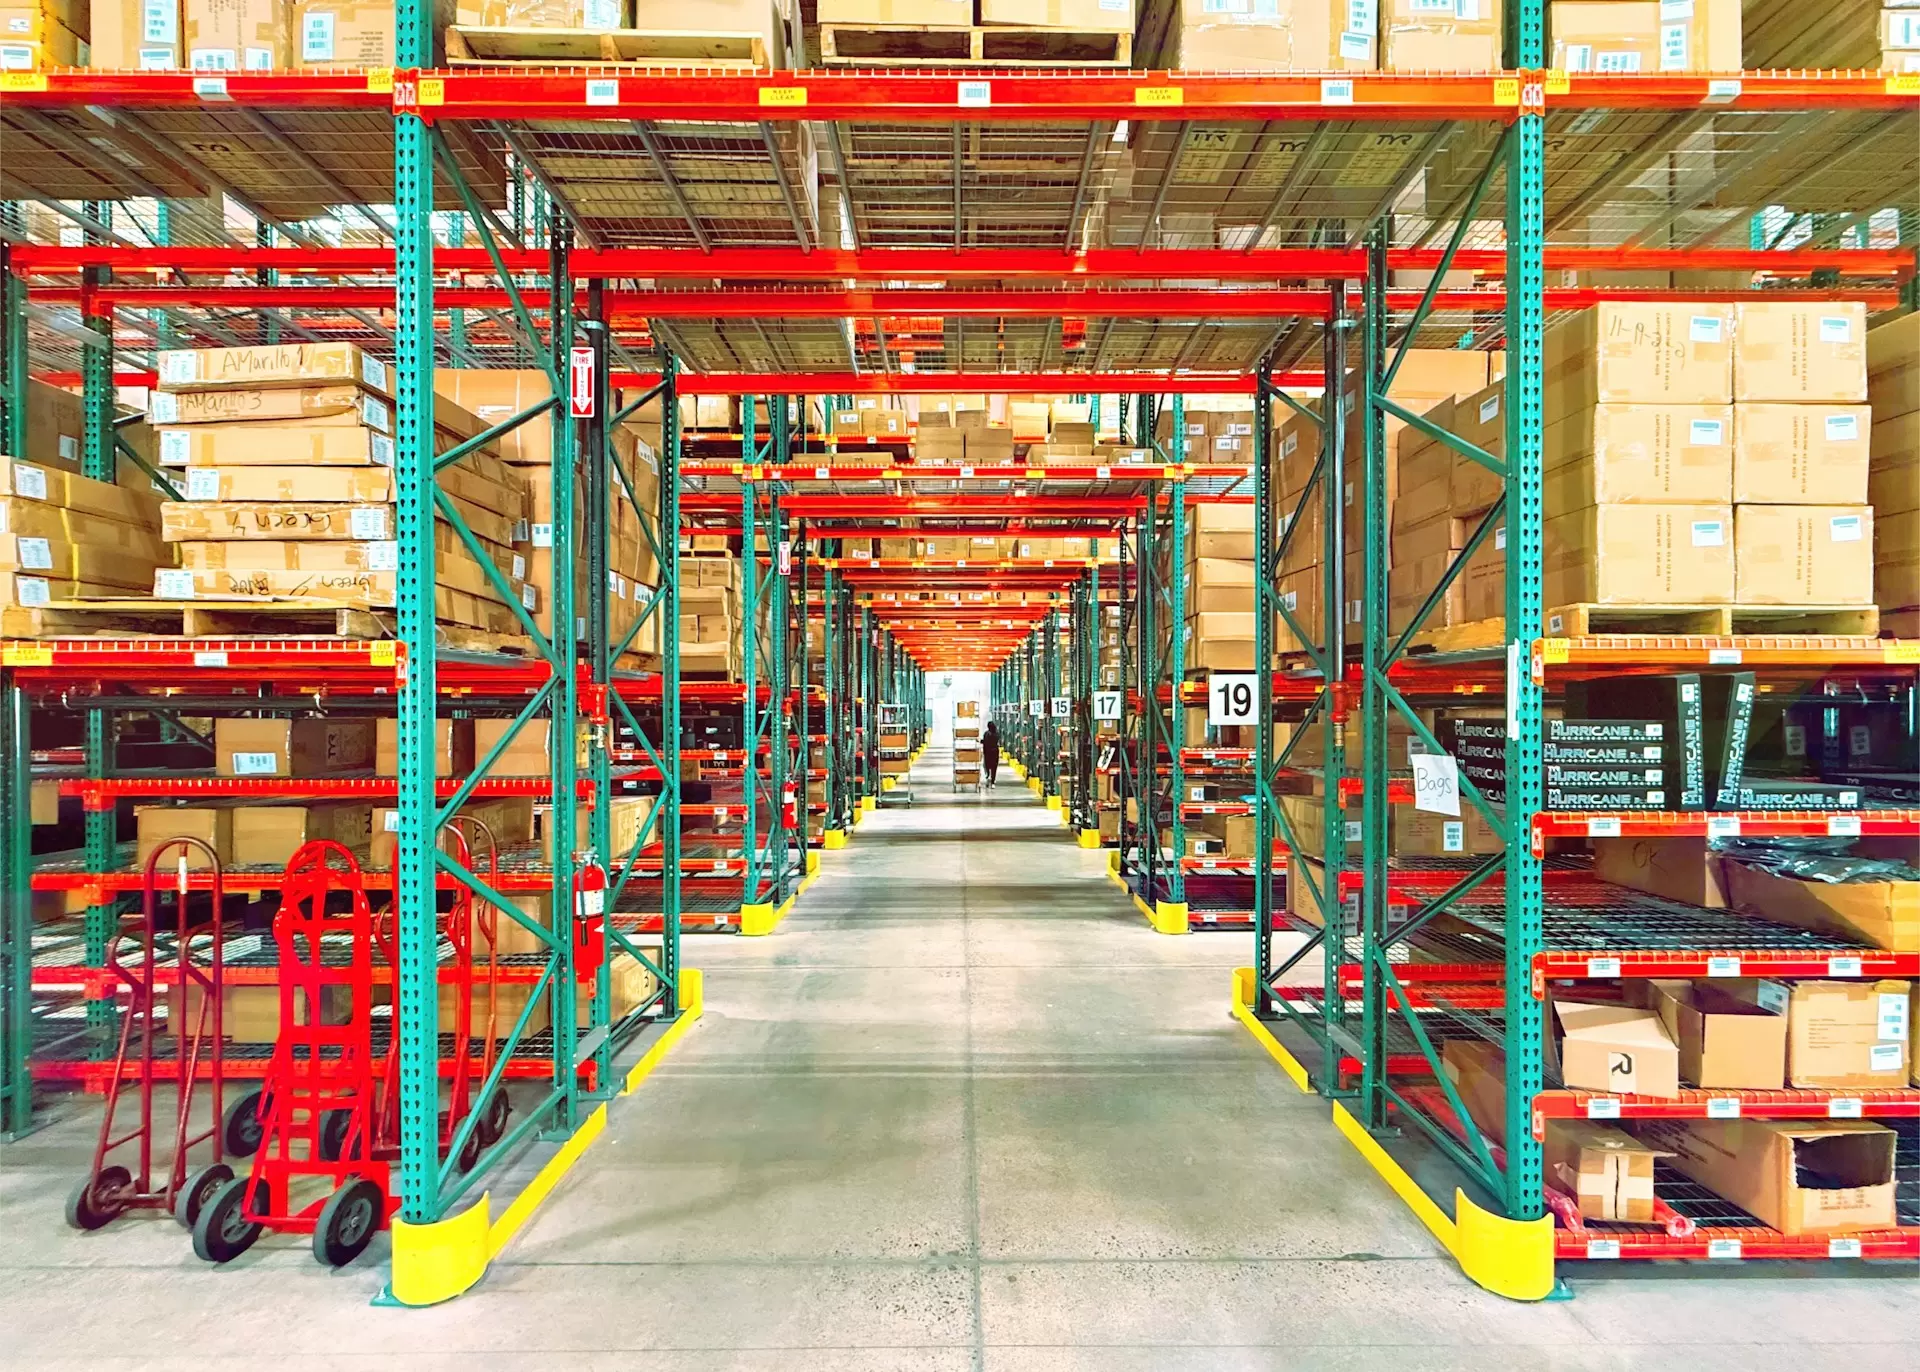
Osborne Park is a busy working suburb in Perth, with plenty of local businesses moving stock, packing orders and keeping shelves full. When a forklift breaks down or the racking runs out of room, you need to act quickly. This article walks through the good and the not-so-good of financing that gear, so you can decide what suits your business.
What Is Warehouse Equipment Finance?
Warehouse equipment finance is a loan or lease used to buy equipment such as forklifts, pallet jacks, racking or conveyors. The equipment itself usually acts as security for the loan, and you repay it in regular instalments over an agreed term.
Lenders often call this equipment finance, and it sits within the wider world of asset finance. Some lenders talk about plant and equipment loans or material handling equipment financing. They all describe much the same thing: borrowing against the item you are buying rather than putting up other property.
The Pros of Financing Warehouse Equipment
The main advantage is that you keep your cash in the business while still getting the equipment you need. That cash can then cover wages, stock, rent and the unexpected bills that every business gets.
There are a few other upsides worth knowing:
- Repayments are fixed in many arrangements, which makes budgeting more predictable.
- The equipment starts earning for you straight away, so it can help pay for itself.
- Because the equipment is the security, you may not need to put your home or other property on the line. This depends on the lender and your circumstances.
- You can often match the loan term to how long the equipment will realistically last.
There is also a tax angle when buying equipment for business. Deductions and depreciation rules can apply, but how they work depends on your structure and the type of finance. Please speak with your accountant before you commit, as the outcome is different for each business.
The Cons of Financing Warehouse Equipment
The main downside is that you pay more than the sticker price once interest and fees are added. You are also locked into repayments even if your orders slow down.
Other trade-offs to weigh up:
- Fees and interest vary between lenders, so the true cost needs a close look.
- If you sell or return the equipment early, break costs may apply.
- A lease with a final balloon payment lowers your regular repayments, but leaves a larger lump sum due at the end.
- Equipment loses value over time, so a long term on a fast-wearing machine can leave you owing more than it is worth for a while.
What Might Financing a Forklift Look Like in Practice?
As an illustration, financing an $80,000 forklift over five years with no balloon payment would cost about $1,575 a month at an illustrative rate of 6.75% p.a. Your actual rate will depend on your lender, business history and the equipment.
Consider a small Osborne Park distribution business that has outgrown its single old forklift. Orders are picking up, but the owner does not want to drain the bank account that covers wages and supplier invoices. A broker compares options and the owner chooses a five-year term so repayments sit comfortably against the extra revenue the second machine brings in.
The outcome is a working forklift on the floor, a repayment the owner can plan around, and a healthy cash buffer left in the bank. The trade-off is that the business pays interest on top of the purchase price and must keep making repayments even in a quiet month. A shorter term would lower the total interest but raise the monthly amount, so it comes down to what the business can carry. You can test different amounts and terms with a finance calculator before you talk to anyone.
Loan or Lease: Which Suits Your Warehouse?
A loan usually leads to you owning the equipment, while a lease often keeps ownership with the lender and lets you use the equipment for a set period. Which suits you depends on how long you will use the gear and how you want to handle the end of the term.
If you plan to run a machine for many years, ownership through a loan may make sense. If your needs change quickly, or you like to upgrade often, a lease can offer flexibility, though you may not own the asset at the end. The tax treatment can differ between the two, so ask your accountant how each would sit in your books.
If you also need to cover day-to-day costs while the new equipment ramps up, working capital loans or broader business loans are worth a look alongside the equipment finance. Each one has its own costs and terms, so it pays to compare them together.
Why Talk to a Broker Before You Sign?
A broker can compare heavy equipment lenders and other finance providers on your behalf, so you are not working through each one alone. We are a local, community-minded team, and we like to understand your business before we suggest anything.
That means looking at the equipment, your cashflow and your plans, then recommending a structure that fits. We will also be upfront about the costs and the risks. You can read more about us if you would like to know who you would be speaking with.
If you are weighing up a forklift, racking system or other warehouse gear, call one of our team or book an appointment at a time that works for you. We will talk through your options over a coffee or a phone call, and help you work out a plan that suits your business.